
Income Insurance Online :: News
SHARE

Share this news item!

Disaster Recovery Gap Puts Retail Resilience in Focus

New QBE-commissioned research shows severe weather can affect small business numbers well beyond the clean-up phase

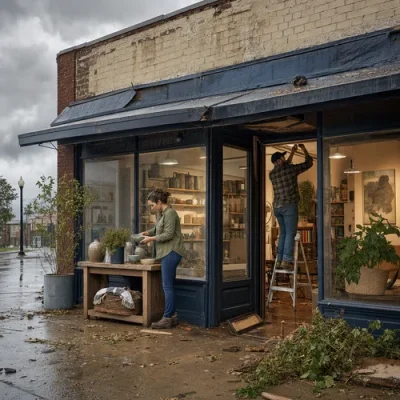
Disaster Recovery Gap Puts Retail Resilience in Focus?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh research commissioned by QBE and conducted by Oxford Economics Australia has put a longer lens on disaster recovery for small businesses, finding that the economic effect of floods, bushfires and cyclones can deepen well after the initial clean-up.
For Australian retailers, the message is practical: recovery planning and insurance settings need to reflect more than the first few weeks after a major event.

The report, released in October 2026, examined seven significant Australian disasters between 2018 and 2023 and compared affected communities with similar areas that were not hit by a major disruption. It estimated that affected regions had around 3% fewer small and medium enterprises than expected in the year of an event, widening to 4% after one year and 9% after two years. By the third year, the gap was still around 7%.

Those figures do not mean every missing business was directly destroyed by weather. QBE’s own commentary notes that disaster can slow new business formation, reduce investment and exhaust the reserves that allow firms to keep trading in the immediate aftermath. Even so, the pattern is important for shop owners because retail recovery often depends on factors outside the shop itself: customer foot traffic, staff availability, freight routes, nearby anchor tenants and whether the broader shopping precinct comes back to life.

This is where insurance design and business continuity planning meet. Property cover may help with damaged fit-out, stock or equipment, depending on the policy. Business interruption cover, where held, raises a different question: how long would revenue realistically take to recover after a major loss? A short indemnity period may look affordable at renewal, but it can be tested if rebuilding approvals, replacement stock, supplier delays or a damaged local economy stretch recovery over many months.

Retailers reviewing common retail disasters should also look beyond the headline insured event. Useful checks include current stock values, seasonal peaks, replacement cost assumptions, lease obligations, flood or storm exclusions, waiting periods, sub-limits and whether temporary trading costs would be recognised. Educational tools can help businesses estimate replacement values, but final cover decisions still depend on policy wording, insurer appetite and the individual business circumstances.

The report is also a reminder of uncertainty. It was commissioned by an insurer and analyses community-level outcomes, not individual claim results. However, its broader point is difficult to ignore: a disaster recovery plan that ends when the doors reopen may be too narrow. For shop owners in exposed locations, resilience is increasingly about surviving the second year as well as the first week.

Published:Thursday, 5th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Isuzu Recall Puts Software Risk on the Insurance Radar
05 Nov 2026: Paige Estritori
A fresh Australian Government vehicle recall for selected Isuzu MY25 trucks is a timely reminder that modern heavy vehicle risk is no longer limited to tyres, brakes, steering, driver behaviour or road conditions. Software faults can also create safety exposures that matter for fleet operations, incident investigations and insurance conversations. - read more
Delayed Insurance Inquiry Keeps Tradie Cover Issues on the Table
05 Nov 2026: Paige Estritori
A federal parliamentary inquiry into small business insurance has pushed its reporting timetable into early 2027, extending the wait for recommendations that may shape future debate on affordability, availability and regulation. For Australian tradespeople, the delay matters because the inquiry is examining the commercial insurance lines many small operators rely on daily, including public liability, professional indemnity, cyber risk and business interruption cover. - read more
Why Claims Communication Is Back in the Spotlight
05 Nov 2026: Paige Estritori
A new Life Code Compliance Committee inquiry has put fresh attention on the way life insurers manage longer-running income protection insurance and total and permanent disability claims, finding that clearer communication and earlier information requests could reduce avoidable stress for people waiting on claim decisions. - read more
New Isuzu Truck Recall Highlights a Claims Evidence Issue
05 Nov 2026: Paige Estritori
A fresh safety recall affecting 3,710 Isuzu MY25 trucks is a timely reminder that modern truck insurance risk is not only about driver behaviour, road conditions or workshop servicing. Software, trailer systems and electronic braking signals can all become part of the evidence trail if an incident occurs. - read more
Mental Health Cover Debate Now Matters for Business Protection
05 Nov 2026: Paige Estritori
Australia’s life insurance sector is moving into a detailed debate over how mental health conditions should be treated in disability-style cover, and the outcome could matter for business owners who rely on insurance to protect income, debt and operational continuity. - read more


Life Insurance Articles

How Income Protection Benefit Payments Are Calculated
Income protection benefit payments are usually based on your insured monthly benefit, your income before disability, policy limits, claim evidence and any offsets that apply. This guide explains the main factors that can affect how much may be paid during an income protection claim in Australia. - read more
Deciphering Your Policy: A Beginner's Guide to Insurance Terminology
Welcome to the world of insurance – a domain where words like 'deductible' and 'premium' can significantly impact your financial protection and peace of mind. As a beginner, grasping the basics of insurance terminology is the first step towards making informed decisions about the policies that safeguard your assets and future. In this guide, we will embark on a journey through the language of insurance, which can often seem as complex as the policies themselves. - read more
Income Safety Net: How to Choose the Right Income Protection for Your Lifestyle
In the face of life's unpredictable twists and turns, few things are as disconcerting as the possibility of suddenly losing your ability to earn an income due to illness. Such events are often unexpected and can have significant financial repercussions that interrupt not only your flow of daily life but also compromise your future plans. - read more
Income Protection Insurance: A Lifeline for Freelancers and Contractors
In today's dynamic gig economy, freelancers and contractors are an essential part of Australia's workforce. Choosing flexibility and autonomy over traditional roles, these professionals enjoy the freedom to manage their schedules and select projects that align closely with their interests. However, this lifestyle brings unique challenges, especially regarding financial security. - read more
Income Protection vs. Life Insurance: What's Best for You?
Financial protection is an essential aspect of sound financial planning. It ensures that you and your family are safeguarded against unexpected events that could lead to financial hardship. Two common types of financial protection are income protection insurance and life insurance. - read more

Knowledgebase
Endorsement:
An amendment or addition to an existing insurance policy that changes the terms or scope of the original policy.